 Wealth Building
Continuing advice and accountability
A financial plan is a map. Nobody reaches a destination holding only a map — someone has to stay on the road with you.
Vetapalem Sridhar · Goal-based planning · April 5, 2024
The product was decided before the doorbell rang. Most financial sales visits are not a diagnosis — they are a delivery.
The product was decided before the doorbell rang.
That is the uncomfortable truth about most financial sales visits. The person at your dining table carries three to five products. Whoever you are — whatever your age, income, loans, or goals — you are leaving that conversation with one of those three to five. The questions asked about your life are not there to shape the recommendation. They are there to shape the pitch for a recommendation that already exists. The visit is not a diagnosis. It is a delivery.
Watch how it plays out. A 25-year-old starting her career meets the agent. So does a 55-year-old two years from retirement. Different lives. Different needs. Often the same recommendation — the same ULIP. Not because it fits both. Because it is in the bag, it is what the agent is authorised to sell, and it is usually the highest-commission product in that bag. The recommendation follows the bag, not the life.
The mutual fund distributor has a different bag and the same limit. Under SEBI's framework he can recommend funds. He is not authorised to build you a comprehensive financial plan — which puts the biggest question of all outside his mandate: is a mutual fund even the right decision for you, this year, given everything else in your life? He cannot answer that question. So it never gets asked.
The bank relationship manager has the widest shelf and the tightest leash. Monthly targets. Quarterly pushes. The products recommended to you this quarter are, to a large extent, the products the bank needs to move this quarter. That is why the recommendation changes every time you visit the branch — not because your life changed, but because the target sheet did. Your "portfolio review" is shaped by the shelf, not by your life.
What does product-first advice produce over ten years? A predictable pattern:
Then the milestone arrives — the college admission, the retirement date — and the money is not where it needs to be. Not because markets failed. Because a decade of purchases was never a plan.
Now notice what is missing from every one of those conversations: a goal. Nobody asked what the money is FOR. Nobody asked when you need it, how much you need, or what happens if you fall short. Without those answers, no product can be right or wrong — which is precisely why any product can be sold.
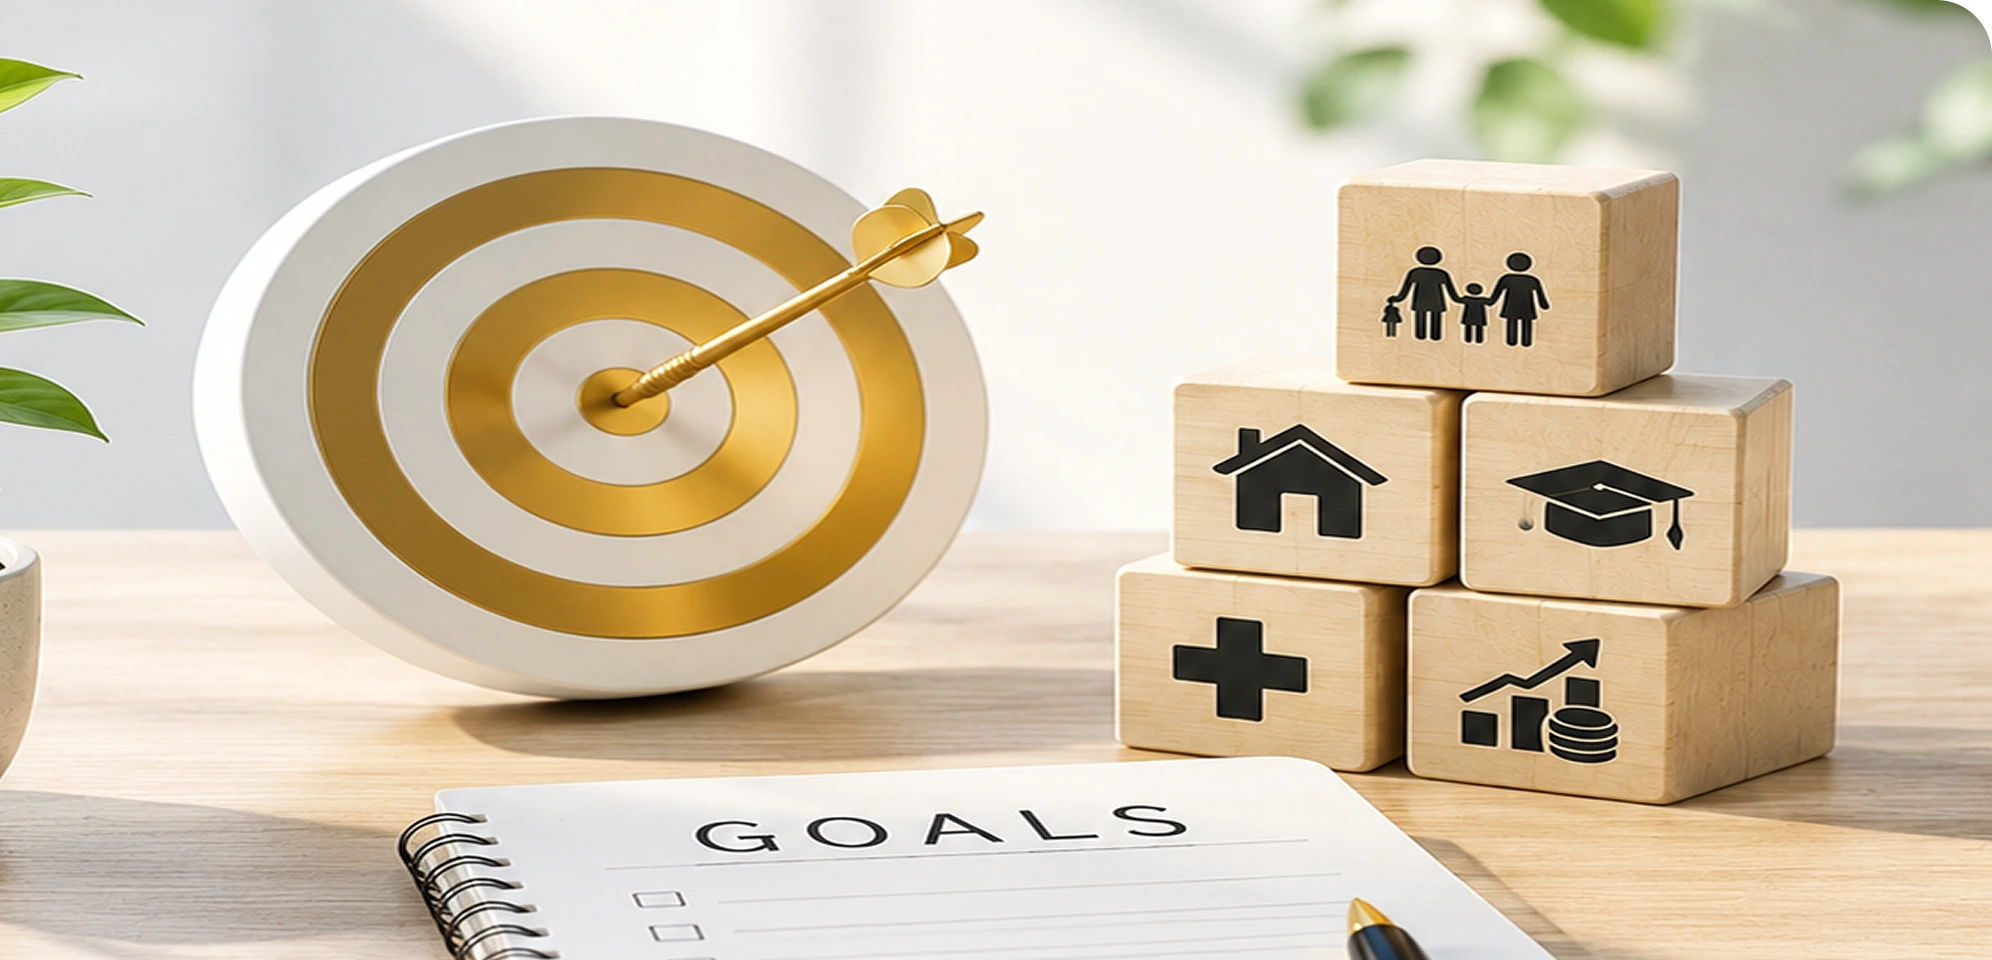
It starts with your goals — the amount, the date, the priority. Then the plan. Then the asset allocation. Products, if needed at all, are the LAST decision, not the first. That sequence is the entire difference between being advised and being sold to. And it is only possible when the person across the table earns from you — not from the bag.
WealthOne
Read More — The Reality · WealthOne
Continue Reading
Wealth BuildingA financial plan is a map. Nobody reaches a destination holding only a map — someone has to stay on the road with you.
 Wealth Building
Who taught you about money? For most of us, the honest answer is whoever was nearby — generous with advice, none of them qualified to give it.
 Investments
What does your financial adviser cost you? If you cannot answer in one number, you already have the answer.